
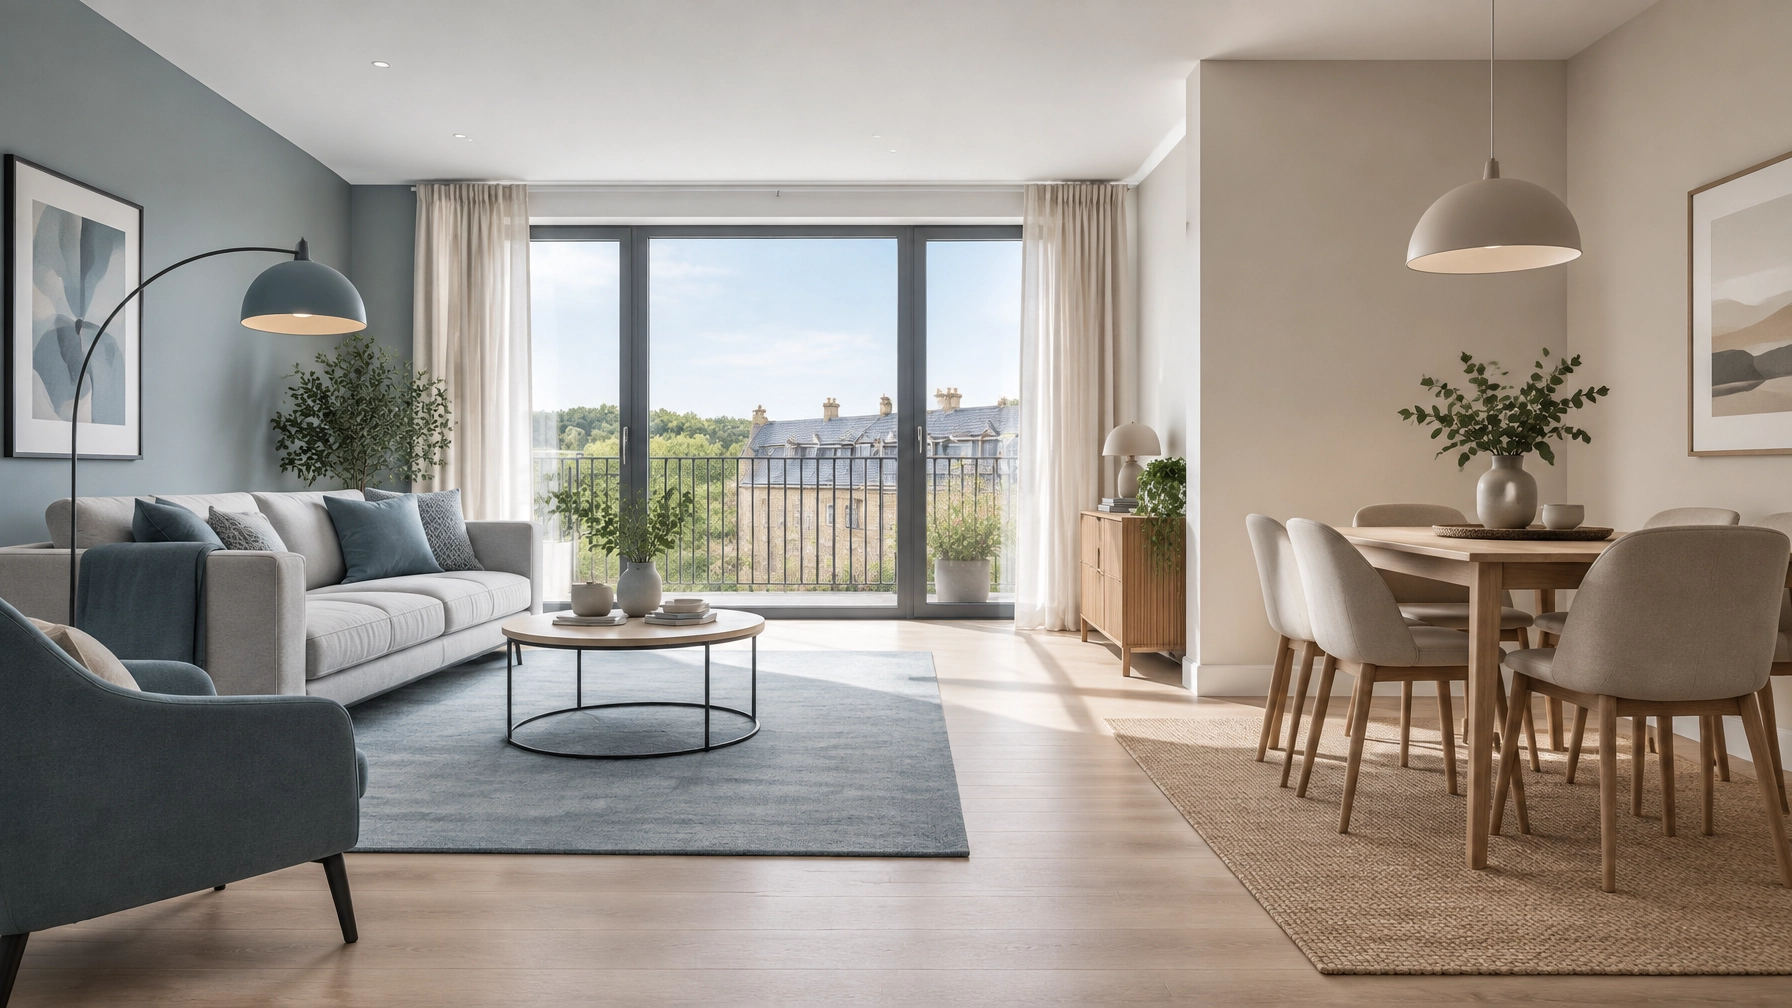
If you are searching for a shared ownership property for sale, you may come across resale homes alongside new-build developments. A shared ownership resale is an existing home being sold by its current shared owner, rather than a property being sold for the first time by a developer or housing association.
Resales can offer established locations, completed communal areas and the opportunity to see the actual property before you buy. However, the process includes specific eligibility checks, valuation requirements and lease conditions.
This guide explains what to review before making an offer.
What is a shared ownership resale?
A shared ownership resale is a property where the current owner is selling their existing share. The housing association or another registered provider continues to own the remaining share.
For example, a seller may own 40% of a property and be selling that 40% share. You would usually purchase that share, then pay:
- A mortgage on the share you own
- Rent to the housing association on its remaining share
- Service charges and other lease-related costs
The exact arrangement depends on the property’s lease. You should ask the housing association or selling agent for the current share, full market value, rent, service charge and remaining lease term.
In many cases, a resale buyer must purchase at least the same share that the current owner holds. This differs from some new-build schemes, where buyers may be able to start with a smaller initial share.
How is a resale different from a new-build shared ownership home?
The main difference is who is selling the property and the condition of the home.
| Shared ownership resale | New-build shared ownership |
|---|---|
| Sold by an existing shared owner | Sold by a developer or housing association |
| The property has already been occupied | The property is usually new and may include a builder’s warranty |
| You typically buy the seller’s existing share | The initial share may be set by the provider |
| You can inspect the completed home before offering | You may be buying from plans or an unfinished development |
| The existing lease and charges need careful review | The provider supplies new-build scheme information |
A resale may also be in a more established area, with clearer information about service charges, communal maintenance and how the development operates. On the other hand, you should inspect the property carefully because its condition will vary.
The Share to Buy step-by-step buying guide provides further information about how shared ownership applications typically work.
Check your eligibility before viewing properties
Eligibility rules apply to most shared ownership properties in England, although individual providers may have additional requirements.
You will usually need to:
- Be aged 18 or over
- Have a gross annual household income of no more than £80,000 outside London or £90,000 in London
- Be unable to afford a suitable home on the open market
- Be a first-time buyer, a former homeowner who cannot currently afford to buy, or an existing shared owner moving home
- Have the right to live in the UK
- Be able to afford the mortgage, rent and service charges
- Have no serious rent or mortgage arrears
You generally cannot own another property when you complete the purchase. If you currently own a home, you will normally need to be selling it and completing that sale as part of the process.
Some properties may have additional requirements, such as a local connection, priority for existing social tenants or age restrictions. Review the individual listing and ask the housing association to confirm the criteria before spending money on a mortgage application or legal work.
Understand the affordability assessment
Passing the headline eligibility criteria does not guarantee approval. The housing association will also need to confirm that the purchase is financially sustainable.
The affordability assessment will usually consider:
- Your household income and employment
- Savings and deposit available
- Existing loans and credit commitments
- Regular household expenditure
- Mortgage payments on the share you are buying
- Rent on the housing association’s remaining share
- Service charges and other property costs
- The effect of possible interest rate or charge increases
A provider may use its own assessment process or a recognised shared ownership affordability calculator. You may be asked to work with an approved financial adviser or specialist mortgage broker.
A mortgage in principle is useful before making an offer. It gives you an indication of the amount a lender may provide, although it is not a final mortgage offer. Make sure the calculation includes the rent and service charge, not just the mortgage payment.

The typical buying process
The process can vary between providers, but a shared ownership resale commonly follows these stages.
1. Search for suitable properties
Use property portals and specialist platforms to compare location, price, share percentage, rent and service charges. When searching for a shared ownership property for sale, check whether the listing is a resale and identify the housing association involved.
2. Review the listing information
Before arranging a viewing, ask for:
- The share being sold
- The full market value
- The current rent
- The current service charge
- The lease length
- Any local eligibility requirements
- Whether the property is subject to a nomination period
- Any restrictions on pets, subletting or alterations
3. Arrange a viewing
A viewing allows you to assess the actual condition, layout and surroundings. Look beyond decoration and consider:
- Windows, doors, heating and plumbing
- Damp, condensation or visible damage
- Communal entrances, lifts and shared areas
- Parking arrangements
- Storage space
- Noise from neighbours, roads or communal equipment
- The condition of balconies, gardens or external areas
You may wish to arrange a survey. Your mortgage lender’s valuation is not the same as a detailed condition survey.
4. Confirm your mortgage position
Obtain or update your mortgage in principle and confirm that the lender accepts the specific shared ownership lease and property type. Some lenders have restrictions relating to lease length, building construction or service charge arrangements.
5. Understand the RICS valuation
The sale price of a shared ownership resale is normally based on the property’s full market value, assessed by an independent RICS-registered valuer. The share price is then calculated from that valuation.
For example, if the full market value is £300,000 and the seller owns 40%, the share price would typically be £120,000.
Ask:
- When was the valuation carried out?
- Is it still valid?
- What full market value was used?
- Does the asking price reflect the stated share?
- Will a new valuation be required if the process takes longer?
The valuation basis and validity period should be confirmed by the housing association and your solicitor. The lease and provider’s rules take precedence.
6. Consider the nomination period
Many shared ownership leases give the housing association a nomination period when the current owner wants to sell. During this period, the provider may market the property to eligible buyers or nominate a buyer.
The length depends on the lease and the shared ownership model. It is often four or eight weeks, but it may differ. If no eligible buyer is found, the seller may be able to market the property more widely, subject to the lease.
As a buyer, this means the housing association may need to approve you even if you find the property through an estate agent. Ask whether the nomination period is still running and what stage the application has reached.
7. Complete the affordability and eligibility checks
You will provide information about your income, savings, expenditure and household circumstances. The provider may also request proof of identity, payslips, bank statements and evidence of your deposit.
8. Instruct a shared ownership conveyancer
Choose a solicitor or licensed conveyancer who regularly handles shared ownership transactions. They should review:
- The lease and resale provisions
- Rent review clauses
- Service charge accounts
- Major works or planned repairs
- Restrictions on alterations and subletting
- Staircasing provisions
- The nomination period
- The housing association’s consent requirements
Once the legal work and mortgage are ready, you exchange contracts and agree a completion date.
Budget for the full cost, not just the share price
The deposit is usually calculated as a percentage of the share you are purchasing, not the full market value. For example, a 10% deposit on a £120,000 share would be £12,000. The lender and your mortgage offer will determine the exact amount.
You should also budget for:
- Mortgage arrangement or broker fees
- Conveyancing and searches
- A survey, if commissioned
- Moving costs
- A possible reservation fee
- Mortgage valuation fees, where applicable
- Rent on the housing association’s unsold share
- Monthly service charges
- Buildings or contents insurance, depending on the lease
- Ground rent or estate charges, if applicable
Stamp Duty Land Tax
Stamp Duty Land Tax treatment for shared ownership can be complicated. Depending on the property and your circumstances, you may be able to pay SDLT on the initial share or make a market value election and pay based on the full property value.
First-time buyer relief may also be relevant if you meet the conditions in force at the time of purchase. The rules can depend on the price, your buyer status and whether you staircase in the future.
Ask your conveyancer to explain the available options using current GOV.UK SDLT guidance before making a decision.
Questions to ask before making an offer
Before offering on a shared ownership property for sale, consider asking:
- What percentage share is being sold?
- What is the full market value of the property?
- When was the RICS valuation completed?
- What are the current monthly rent and service charges?
- How are rent and service charges reviewed?
- Are there planned major works or service charge increases?
- How long is left on the lease?
- Is the property still within the nomination period?
- What eligibility or local connection rules apply?
- Can the buyer staircase, and what restrictions apply?
- Are pets, subletting or alterations restricted?
- What fixtures, fittings and parking rights are included?
- Has the property had any disputes, leaks or insurance claims?
- Which housing association will approve the purchase?
- What documents will be provided to my solicitor?
Obtain answers in writing where possible. This gives your solicitor a clearer record during conveyancing.

Practical buyer checklist
Use this checklist before you make an offer:
- Confirm you meet the income and ownership criteria
- Check whether the property has additional local or scheme restrictions
- Obtain a mortgage in principle
- Calculate mortgage, rent and service charges together
- Confirm the share being sold and the full market value
- Review the RICS valuation date
- Attend a thorough viewing
- Ask about major works and planned service charge increases
- Check the remaining lease term
- Estimate your deposit and purchase costs
- Ask a conveyancer to explain SDLT treatment
- Instruct a solicitor experienced in shared ownership
- Confirm the nomination period and provider approval process
Find shared ownership resales with PE Homes
Buying a shared ownership resale is more straightforward when the listing information is clear and the relevant parties communicate promptly.
PE Homes specialises in shared ownership sales and helps sellers market properties across Rightmove, Zoopla and PrimeLocation, as well as Share to Buy. Our online estate agency model provides professional marketing, viewing request management, offer negotiation and sale progression for a fixed fee of £500.
To understand more about our shared ownership service, visit the PE Homes website or contact the team. Always confirm the specific eligibility, lease and affordability requirements with the housing association, mortgage adviser and conveyancer involved in your purchase.



Leave A Comment